Showing posts with label March 2018. Show all posts

Issue of Equity Shares Solution | March 2018 HSC Board

Issue of Equity Shares Solution: March 2018 HSC Board

Q. 5. Issue of Equity Shares

March 2018 HSC Board Paper Solution

Refer to the question paper images below.

HSC Accounts March 2018 Question Paper - Page 8 (Q5 Dissolution/Issue of Shares) HSC Accounts March 2018 Question Paper - Page 9 (Q6 NPO)

Journal of Aniket Ltd.

In the books of the Company
Swipe table left/right to view amounts →
Date Particulars L.F. Debit (Rs.) Credit (Rs.)
(1)
Bank A/cDr.
To Equity Share Application A/c
[Being application money received on 50,000 shares @ Rs. 20]
10,00,000
10,00,000
(2)
Equity Share Application A/cDr.
To Equity Share Capital A/c
To Equity Share Allotment A/c
[Being share application money transferred to share capital A/c and excess amount adjusted to allotment money]
10,00,000
8,00,000
2,00,000
(3)
Equity Share Allotment A/cDr.
To Equity Share Capital A/c
[Being Share allotment money due on 40,000 shares @ Rs. 30]
12,00,000
12,00,000
(4)
Bank A/cDr.
To Equity Share Allotment A/c
[Being share allotment money received]
10,00,000
10,00,000
(5)
Equity Share First Call A/cDr.
To Equity Share Capital A/c
[Being share first call amount due on 40,000 shares @ Rs. 30]
12,00,000
12,00,000
(6)
Bank A/cDr.
To Equity Share First Call A/c
[Being share first call amount received on 39,000 shares]
11,70,000
11,70,000
(7)
Equity Share Second Call A/cDr.
To Equity Share Capital A/c
[Being share second call amount due on 40,000 shares @ Rs. 20]
8,00,000
8,00,000
(8)
Bank A/cDr.
To Equity Share Second Call A/c
[Being share second call amount received on 39,000 shares]
7,80,000
7,80,000
(9)
Equity Share Capital A/cDr.
To Equity Share First Call A/c
To Equity Share Second Call A/c
To Equity Share Forfeiture A/c
[Being 1,000 shares forfeited on account of non-payment of first and second call]
1,00,000
30,000
20,000
50,000

Dissolution of Partnership Solution | March 2018 HSC Board

Dissolution of Partnership Solution: March 2018 HSC Board

Q. 5. Dissolution of Partnership

March 2018 HSC Board Paper Solution

Refer to the question paper images below.

HSC Accounts March 2018 Question Paper - Page 7 (Q4 Bills of Exchange) HSC Accounts March 2018 Question Paper - Page 8 (Q5 Dissolution/Issue of Shares)

In the books of the firm

Complete Solution

Realisation Account

Swipe left/right to view details →

Partners' Capital Accounts

Swipe left/right to view all partners →

Bank Account

Swipe left/right to view details →

Bills of Exchange Solution | March 2018 HSC Board Paper

Bills of Exchange Solution: March 2018 HSC Board

Q. 4. Bills of Exchange

March 2018 HSC Board Paper Solution

Refer to the question paper image below.

HSC Accounts March 2018 Question Paper - Page 7 (Q4 Bills of Exchange)

Journal Entries

In the books of Sayali
Swipe table left/right to view amounts →
Date Particulars L.F. Debit (Rs.) Credit (Rs.)
(1)
Manali’s A/cDr.
To Sales A/c
[Being the goods are sold]
40,000


40,000
(2)
Bills Receivable A/cDr.
To Manali’s A/c
[Being the bill is drawn]
40,000


40,000
(3)
Bank A/cDr.
Discount A/cDr.
To Bills Receivable A/c
[Being the bill is discounted]
38,800
1,200


40,000
(4)
Manali’s A/cDr.
To Bank A/c
[Being the bill is dishonoured and noting charges charged]
40,300


40,300
(5)
Manali’s A/cDr.
To Interest A/c
[Being the interest is charged]
750


750
(6)
Cash A/cDr.
To Manali’s A/c
[Being the part payment is made along with Noting charges]
20,300


20,300
(7)
Bills Receivable A/cDr.
To Manali’s A/c
[Being the new bill is drawn along with interest]
20,750


20,750
(8)
Manali’s A/cDr.
To Bills Receivable A/c
[Being the bill is dishonoured]
20,750


20,750
(9)
Cash A/cDr.
Bad debts A/cDr.
To Manali’s A/c
[Being the drawee become insolvent and only 40 % of the amount could be recovered from her private estate]
8,300
12,450


20,750

Death of a Partner Solution | March 2018 HSC Board Paper

Death of a Partner Solution: March 2018 HSC Board

Question: Death of a Partner

March 2018 HSC Board Paper (Q3)

Refer to the question paper images below.

HSC Accounts March 2018 Question Paper - Page 6 (Q3 Death / Q4 Bills - Part 1) HSC Accounts March 2018 Question Paper - Page 6 (Q3 Death / Q4 Bills - Part 2) HSC Accounts March 2018 Question Paper - Page 7 (Q4 Bills of Exchange)

In the books of the firm

Complete Solution

Profit and Loss Adjustment A/c

Swipe left/right to view details →

Manish's Capital A/c

Swipe left/right to view details →

Working Notes

1. Working of Manish’s Share of Profit:

Formula: \( \text{Previous year's Profit} \times \text{Profit Sharing Ratio} \times \text{Period} \)

$$ 96000 \times \frac{1}{6} \times \frac{6}{12} = 6000 $$

2. Working of Manish’s Share of Goodwill:

Average Profit Calculation:

$$ \text{Average Profit} = \frac{48000 + 80000 + 76000 + 96000}{4} = \frac{300000}{4} = 75000 $$

Firm's Goodwill (4 times Average Profit):

$$ 75000 \times 4 = 300000 $$

Manish's Share of Goodwill:

$$ 300000 \times \frac{1}{6} = 50000 $$

(Note: There is a discrepancy in the provided solution image which shows 40000. However, based on the calculation 50000 is mathematically correct. If following the image strictly: 40000 is used in the ledger).

Admission of Partner Solution | March 2018 HSC Board Paper

Question: Admission of Partner

March 2018 HSC Board Paper (Q3)

Please review the problem details in the images below.

In the books of the firm

Complete Solution

Profit and Loss Adjustment A/c

Swipe left/right to view details →

Partners Capital A/c

Swipe left/right to view all partners →

Balance Sheet

As on 1st April 2016
Swipe left/right to view amounts →
HSC Accounts March 2018 Question Paper - Page 5 (Q3 Admission/Retirement) HSC Accounts March 2018 Question Paper - Page 6 (Q3 Death / Q4 Bills - Part 1)

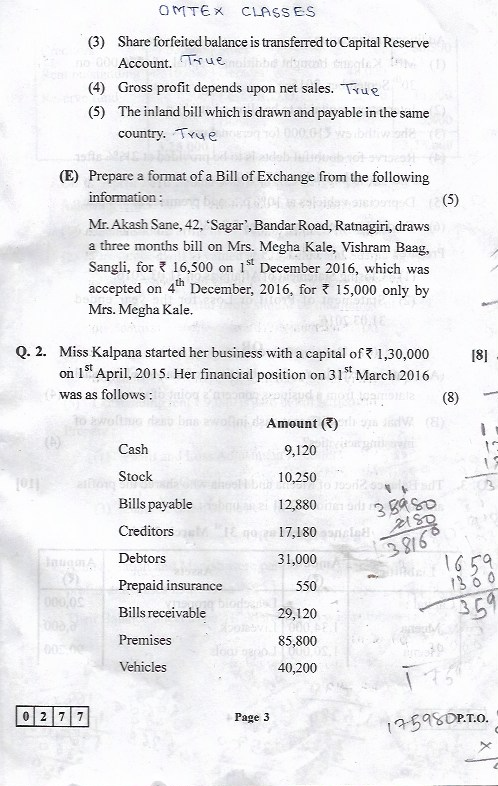
Single Entry Solution Miss Kalpana | March 2018 HSC Accounts Board Paper

Single Entry Solution

March 2018 HSC Board Paper

In the books of Miss Kalpana

Closing Statement of Affairs as on 31st March, 2016
Swipe table left/right to view amounts →
Liabilities Amount Assets Amount
Bills payable 12,880 Cash 9,120
Creditors 17,180 Stock 10,250
Capital (Balancing Figure) 1,75,980 Debtors 31,000
Prepaid Insurance 550
Bills Receivable 29,120
Premises 85,800
Vehicles 40,200
Total 2,06,040 Total 2,06,040

Statement of Profit or Loss

For the year ended 31st March, 2016
Swipe table left/right to view amounts →
Particulars Amount (Rs.) Amount (Rs.)
Capital at the end of the year. 1,75,980
Add: Drawings during the year 10,000
1,85,980
Less: Additional Capital Introduced - 20,000
Adjusted Closing capital 1,65,980
Less: Capital at the beginning of the year. - 1,30,000
Profit Before Adjustments 35,980
Add: Incomes and Gains during the year
Decrease in the value of creditors 2,180
38,160
Less: Expenses and losses During the year.
(1) Interest on Capital (6500 + 500) 7,000
(2) Bad debts 1,000
(3) Reserve for Doubtful Debts 750
(4) Depreciation on Vehicles 4,020
(5) Depreciation on Premises 4,290 - 17,060
NET PROFIT 21,100
HSC Accounts March 2018 Question Paper - Page 3 HSC Accounts March 2018 Question Paper - Page 5 (Q3 Admission/Retirement)